Look Ahead Bias: Defense M&A and Ticker Roll Case Study
An empirical quantitative case study examining how statutory defense procurement disclosure lags, corporate mergers, and survivorship assumptions introduce systemic look-ahead bias into alternative data pipelines, evaluated across 650,000+ federal transactions.
In quantitative finance and algorithmic strategy design, look ahead bias represents one of the most pervasive failure modes in strategy simulation. Look ahead bias occurs when a statistical model inadvertently incorporates information that was physically inaccessible or legally confidential to market participants at the simulated point in time. While classical econometricians frequently guard against obvious forward-looking leakages—such as utilizing end-of-day closing prices to calculate intraday entry signals—the proliferation of alternative datasets, government spending disclosures, and corporate procurement pipelines has introduced subtle structural leaks.
When quantitative research teams ingest public procurement records, they frequently assume that the date appearing on a government award represents the timestamp when the broader market could trade on that information. In reality, federal procurement data is governed by statutory confidentiality delays, multi-tiered corporate subsidiary hierarchies, and complex corporate mergers. Without rigorous, effective-dated entity resolution, historical simulations credit billions of dollars in federal revenue to surviving parent tickers months before those corporations existed in their modern form. To examine these failure modes, this case study dissects the structural mechanics of federal contracting data, tracking how statutory publication lags and corporate restructurings distort historical strategy integrity across our federal contract intelligence radar.
How Look Ahead Bias Distorts Quantitative Financial Models
The mathematical consequence of look ahead bias in quantitative research is the creation of statistical mirages: strategies demonstrate immaculate Sharpe ratios, negligible drawdowns, and robust historical profitability, yet decay immediately upon deployment in live capital environments. In alternative data modeling, this distortion stems from a fundamental divergence between the activity date (when an event took place in the physical world) and the publication date (when the official public record was finalized, ingested, and disseminated to market participants).
Consider an investment model designed to capture corporate revenue acceleration from federal procurement awards. If an algorithm timestamps an award on its formal contract signing date, it assumes an institutional trader possessed perfect foreknowledge during the intervening weeks or months before the public ledger disclosed the transaction. Across 850,000+ resolved events in public federal history, the gap between event occurrence and public disclosure varies widely across reporting regimes:
- Congressional Trading Disclosures: Legislative stock transactions carry a median reporting delay of 27 days, with the 90th percentile reaching 63 days across 63,122 trades recorded since 2018.
- Corporate Lobbying Filings: Quarterly lobbying expenditure reports are posted with a median lag of 20 days (and a 90th percentile of 21 days) following the close of the reporting calendar quarter across 8,975 filings.
- Corporate Insider Disclosures: Form filings by corporate directors and executive officers exhibit a median publication lag of 1 day, expanding to 4 days at the 90th percentile across 35,226 recorded filings.
- Department of Defense Contracts: Defense procurement actions are governed by statutory national security exemptions that enforce a mandatory 90-day publication hold.
Dating historical simulations by activity date rather than verified publication timestamps fundamentally invalidates model integrity. By injecting data early by 20 to 90 days, simulations capture subsequent equity price movements as predictive performance, when in truth the strategy is simply trading on look-ahead leakage.
The Statutory Defense Disclosure Lag: The 90-Day Information Gap
Under Title 10 of the United States Code and the Federal Acquisition Regulation (FAR), military procurement actions are subjected to rigorous operational security reviews prior to public dissemination. To prevent foreign adversaries from piecing together real-time logistical movements, ordnance stockpiling, and technological development timelines, the Department of Defense (DoD) enforces a statutory 90-day embargo on detailed transaction records published to public spending ledgers.
In an empirical 3% block sample of FY2018+ federal contract transactions valued at $1 million or greater, defense procurement accounts for approximately 59% of transaction rows and 65% of total obligated dollars ($111.9 billion out of $170.9 billion sampled, measured October 2026). Consequently, nearly two-thirds of all capital allocated across major federal prime contractors is governed by this 90-day disclosure delay.
This statutory mechanism creates an asymmetric disclosure structure that traps uncalibrated quantitative pipelines:
- Daily Defense Contract Bulletins: For awards exceeding statutory reporting thresholds (typically $7.5 million), the Pentagon releases daily summary announcements at 17:00 Eastern Time on business days. These announcements detail the recipient, obligated amount, and contracting military branch on the day of award.
- Official Public Spending Transactions: The corresponding granular contract transaction records—containing the line-item product service codes, parent entity DUNS/UEI identifiers, subcontract requirements, and pricing schedules—do not appear on public award ledgers until exactly 90 days later.
- Empirical Announcement Lead: Across 9,158 defense contracts appearing in both daily announcements and public transaction ledgers since FY2018, daily bulletins preceded the public transaction records in 93.5% of cases by a median of 90 days (10th percentile 85 days, 25th percentile 90 days, 75th percentile 90 days, 90th percentile 91 days), representing $1.07 trillion in announced defense obligations.
If a quantitative model consumes federal award ledgers without cross-referencing daily contract announcements, it operates under a 90-day information deficit. Conversely, if a researcher trains a model on granular transaction tables using the historical signature date as the observation timestamp, the model peeks three full months into the future.
Defense M&A Case Study: The Raytheon Technologies (RTX) Ticker Transition
The interaction between the 90-day defense disclosure lag and corporate mergers creates severe entity resolution anomalies. A prominent real-world case study is the mega-merger between United Technologies Corporation (historically traded under ticker UTX) and Raytheon Company (historically traded under ticker RTN) to form Raytheon Technologies (traded under ticker RTX).
The corporate restructuring followed a rigid corporate and legal timeline during early 2020:
- Mid-January 2020: A specialized defense division operating under United Technologies signs a classified multi-million-dollar defense avionics contract. The signature date (action date) is recorded in military procurement databases as January 15, 2020. Under statutory rules, the award is withheld from public transaction ledgers for 90 days.
- April 3, 2020: United Technologies successfully completes its all-stock merger of equals with Raytheon Company. United Technologies spins off its non-aerospace commercial businesses (Otis Worldwide and Carrier Global), renames the surviving parent entity Raytheon Technologies, and changes its New York Stock Exchange ticker symbol from UTX to RTX. Concurrently, Raytheon Company (RTN) is delisted and ceases trading.
- Mid-April 2020: The 90-day statutory embargo expires, and the transaction details appear on public federal ledgers on April 15, 2020.
When an automated data pipeline parses this record without point-in-time graph intelligence, it encounters two conflicting failure modes:
- Failure Mode A (Retrospective Surviving Join): The pipeline maps the contract recipient through today's corporate parent lookup table. It observes that the subsidiary belongs to Raytheon Technologies (RTX) and stamps the historical January 15, 2020 transaction with ticker RTX. An algorithmic strategy simulating early 2020 attempts to execute positions in ticker RTX—a financial asset that did not exist on financial exchanges on January 15, 2020.
- Failure Mode B (Static Point-of-Signature Lookup): The pipeline checks corporate registries on the January 15 action date, correctly identifying United Technologies (UTX). However, it timestamps public availability as April 15, 2020 (when the data became public) while retaining the historical ticker UTX. An execution model processing the feed on April 15 attempts to trade UTX, which had ceased trading 12 days prior.
The correct point-in-time resolution standard resolves both dilemmas simultaneously: the signing entity is permanently archived in the primary entity record (documenting who performed the industrial work), while the assigned market ticker rolls dynamically to the security actively traded by market participants on the exact day the record became public. In the United Technologies transition, the contract action published on April 15, 2020 rolls to ticker RTX, matching exchange reality.
Quantifying the Misattribution: How Surviving Entity Mapping Distorts Historical Simulations
The Raytheon merger is not an isolated edge case. Across the United States defense industrial base, corporate consolidation, spin-offs, and divestitures are routine operational realities. When research teams rely on static parent corporate registries—linking historical recipient identifiers to current corporate owners—the resulting misattribution introduces substantial distortions into quantitative datasets.
To quantify the exact empirical scale of this error, our research team audited 197,201 ticker-resolved federal contract transactions representing $2.7 trillion in obligated capital from FY2018 through October 2026. Comparing point-in-time parent links against a static "current parent" table revealed substantial capital dislocation:
- Dollar Misattribution: Mapping resolved federal contract transactions through current parent tables instead of the parent entity valid on each publication date incorrectly reassigns $89.6 billion in federal contract awards—representing 3.31% of total transacted procurement capital across 8,568 distinct contract actions.
- Post-Close Ticker Rolls: Exactly 659 federal contract actions were signed before an acquisition legally closed but published after the transaction was finalized under statutory defense reporting delays. Within this cohort, 651 contract actions rolled to the publicly listed surviving acquirer (including 361 actions rolling to RTX, 124 to LHX following the L3-Harris merger, 49 to UTX, 49 to General Dynamics GD, 43 to Northrop Grumman NOC, and 25 to SAIC), while 8 actions involved acquisitions by unlisted private entities, correctly carrying no trading ticker.
- Ticker Changes Mid-Flight: An additional 254 contract actions involved corporations that changed ticker symbols between contract signing and public disclosure. These transactions (including 121 actions transitioning from UTX to RTX, 68 from HRS to LHX, 44 from JEC to Jacobs J, and 17 from ASGN to EFOR) must carry the newly traded ticker on the publication date rather than their historical predecessor symbol.
When quantitative researchers historical simulation sector-neutral momentum or event-driven factor strategies, allocating $89.6 billion to incorrect balance sheets systematically corrupts factor loadings. In defense contracting analysis, evaluating top prime suppliers requires clean separation between pre-acquisition performance and post-merger integration, as discussed in our research on top defense contractors by revenue.
Point-in-Time Subsidiary Resolution: The Multi-Hop Ownership Challenge
A secondary structural driver of look ahead bias and misattribution in procurement data is corporate subsidiary hierarchy. Large defense conglomerates do not bid on federal solicitations under their listed holding company names. Instead, awards are formally granted to operating subsidiaries, joint ventures, research laboratories, and recently acquired private vendor entities.
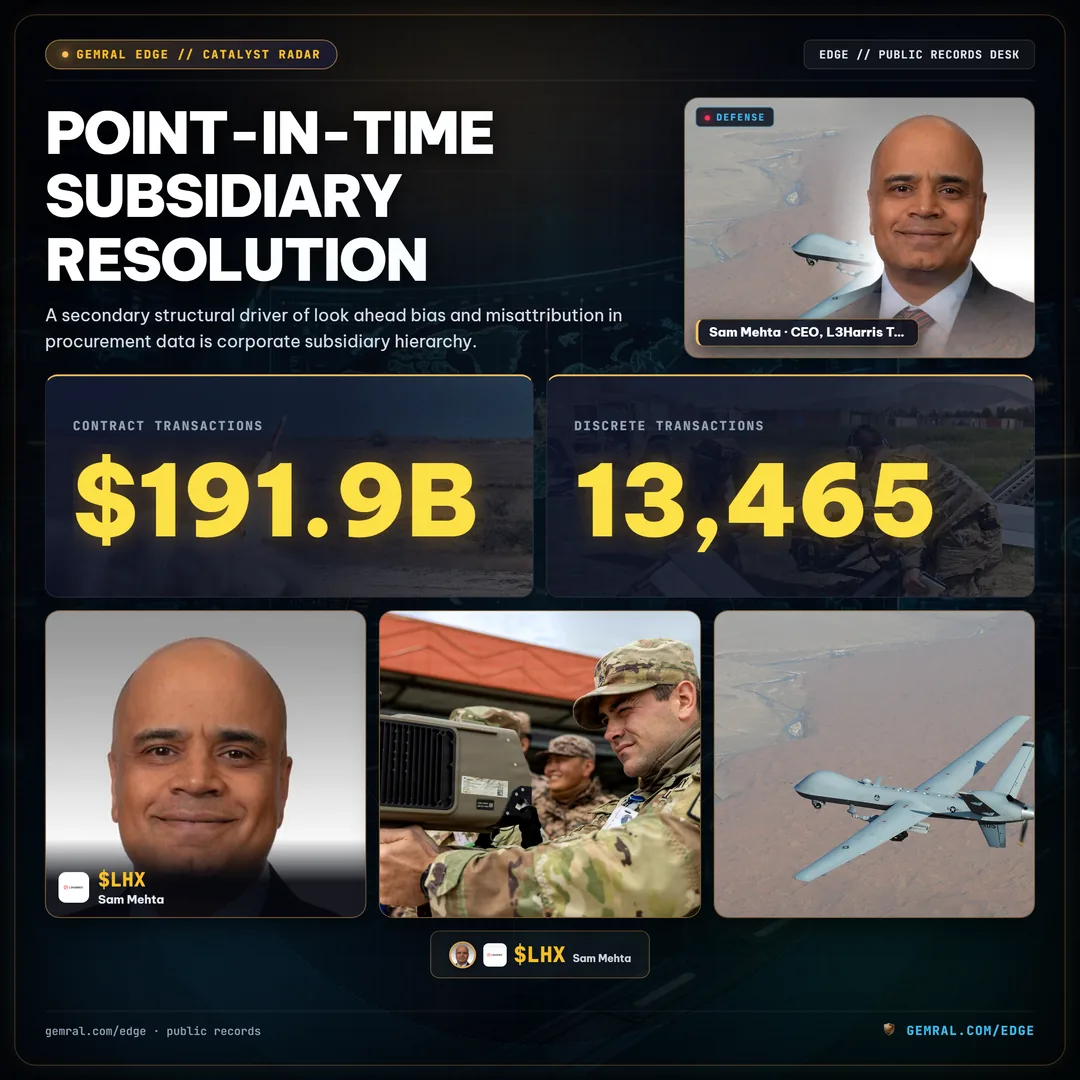
Naive string-matching algorithms that scan federal ledgers for corporate ticker symbols capture only a fraction of total procurement capital. In our verified federal contract database:
- Subsidiary Dependency: A total of $191.9 billion in ticker-linked contract transactions—representing 7.1% of total contract dollars and 13,465 discrete transactions—reaches a listed corporate parent exclusively through an effective-dated subsidiary relationship. On the primary award document, the recipient legal name is an unlisted operating entity with zero lexical resemblance to the parent ticker.
- Effective-Dated Corporate Graph: Corporate subsidiaries are dynamic corporate assets. A subsidiary owned by General Dynamics in 2019 may be divested to private equity in 2022 and subsequently acquired by L3Harris in 2025. Attributing a 2019 contract action using a flat, unversioned relationship table results in retroactive capital theft across corporate balance sheets.
- Contract Dollar Coverage Scope: About 49.3% of FY2018+ federal contract transaction dollars ($1M+) in our database are mapped to a publicly listed ticker (measured October 23, 2026). The remaining procurement volume reflects awards granted to private enterprises, state and municipal entities, educational institutions, or foreign governments that do not possess public equity securities.
Solving the multi-hop subsidiary challenge requires tracking corporate relationships as point-in-time temporal graphs, where parent-subsidiary edges possess strict effective_from and effective_to calendar timestamps. When combined with commercial intelligence platforms detailed in our analysis of GovWin pricing and procurement alternatives, point-in-time graphs allow institutional researchers to trace capital flows from line-item agency obligations directly to public parent corporate balance sheets.
How Quantitative Research Teams Can Eliminate Look-Ahead Bias in Alternative Data
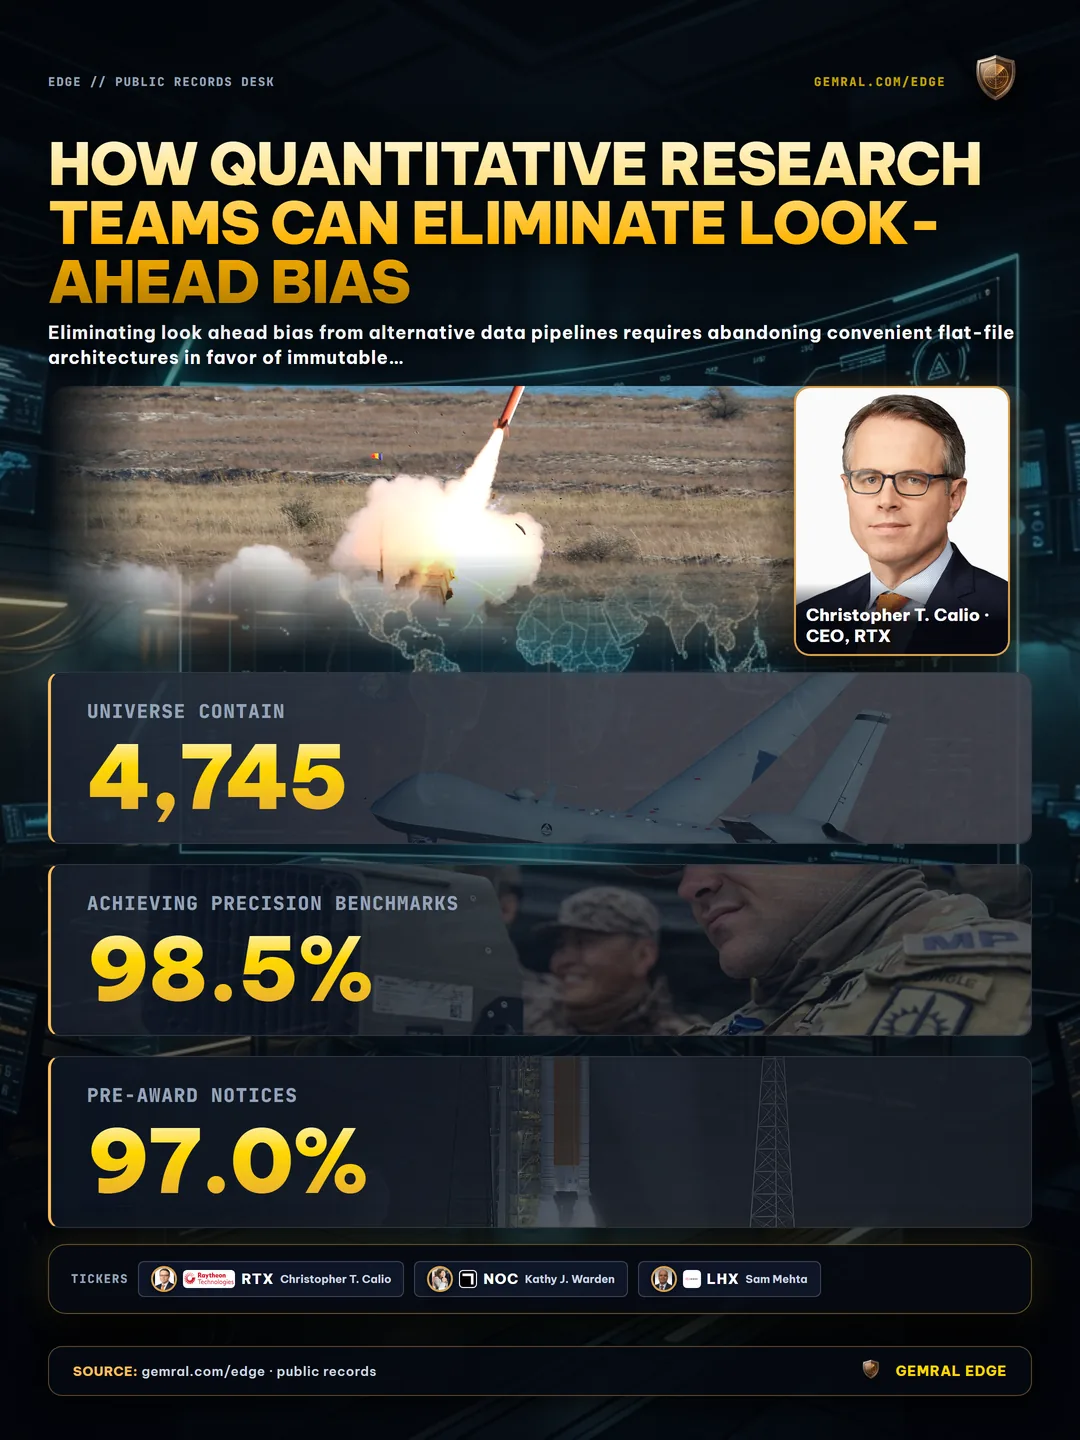
Eliminating look ahead bias from alternative data pipelines requires abandoning convenient flat-file architectures in favor of immutable, point-in-time data engineering protocols. Quantitative research desks and risk managers should enforce four baseline architectural standards across their procurement ingestion pipelines:
- Bifurcate Observation and Publication Timestamps: Every transaction record must store two immutable calendar fields: the event timestamp (contract signature date) and the public dissemination timestamp (when the record cleared statutory review and appeared on public ledgers). All strategy historical simulations and factor models must key strictly on publication timestamps.
- Preserve Delisted and Acquired Universe Entities: A survivorship-free equity universe must contain all 4,745 distinct tickers that traded across historical observation windows, including bankrupt entities, acquired defense primes, and superseded ticker symbols. Delisted entities must retain their original historical identifiers.
- Enforce Sampled Accuracy Verification: Automated pipelines must subject raw procurement feeds to rigorous quality gates. Across 10 primary federal record categories in our data infrastructure, records are subjected to sampled verification against original government source documents, achieving precision benchmarks of 98.5% on contract transactions, 97.0% on pre-award notices, and 97.0% on bid protest dockets.
- Implement Immutable Amendment Ledgers: In federal procurement, contract awards are frequently modified, de-obligated, or formally protested. Rather than retroactively updating past database rows—which silently injects modern revisions into historical data—pipelines must treat updates as append-only revision events with their own discrete publication timestamps.
Institutional quantitative funds and asset managers conducting operational due diligence on alternative data providers can review our comprehensive architecture documentation via our institutional Due Diligence Questionnaire (DDQ) and explore point-in-time federal records directly at gemral.com/edge/contracts.
Public data · not investment advice. All empirical metrics, contract values, corporate timelines, and statutory disclosure intervals cited in this research are derived exclusively from public federal procurement registries, legislative transparency archives, and official corporate filings. This research contains no material non-public information (MNPI) and does not constitute financial, legal, or investment advice. Past performance, historical simulation simulations, and historical contract attributions do not guarantee future investment returns.
Frequently asked questions
What is look ahead bias in quantitative financial models?
Look ahead bias is a modeling error where information from future dates leaks into historical simulation backtests. This leads to artificially inflated Sharpe ratios and statistical illusions of profitability that inevitably fail during live execution.
Why does the Department of Defense enforce a 90-day contract publication lag?
Federal acquisition statutes mandate a 90-day publication delay on sensitive defense procurement actions to protect operational security and industrial logistics. Models dating awards by action date instead of publication date introduce three full months of future look-ahead.
How does defense M&A distort point-in-time contract attribution?
When companies merge or change tickers (e.g., United Technologies UTX merging with Raytheon RTN into RTX), mapping historical contracts through today's corporate parent improperly credits pre-merger revenue to surviving tickers, distorting historical revenue exposure.
How can quantitative research teams eliminate look-ahead bias in procurement data?
Research teams must use point-in-time entity resolution graphs with effective-dated parent-subsidiary links, record exact publication timestamps rather than signature dates, retain delisted and acquired tickers in historical universes, and enforce immutable audit ledgers.